- Focus first on liability protection, because it is the core shield if you cause damage or injury to others
- Match deductibles and coverage types to the car’s value, your savings, and your risk tolerance
- Review exclusions, discounts, and policy details so you know what is covered before you need to file a claim
Choosing car insurance is less about finding the cheapest quote and more about matching coverage to the way you actually drive, the value of your vehicle, and the amount of financial risk you can afford to carry yourself. A policy that looks affordable can still leave you exposed to repair costs, medical bills, liability claims, or a car you cannot replace. On the other hand, paying for coverage you do not need can drain your budget month after month. The right approach is to separate required protection from optional protection, then weigh deductible levels, limits, and exclusions against your savings and driving habits.
Start with what coverage you actually need
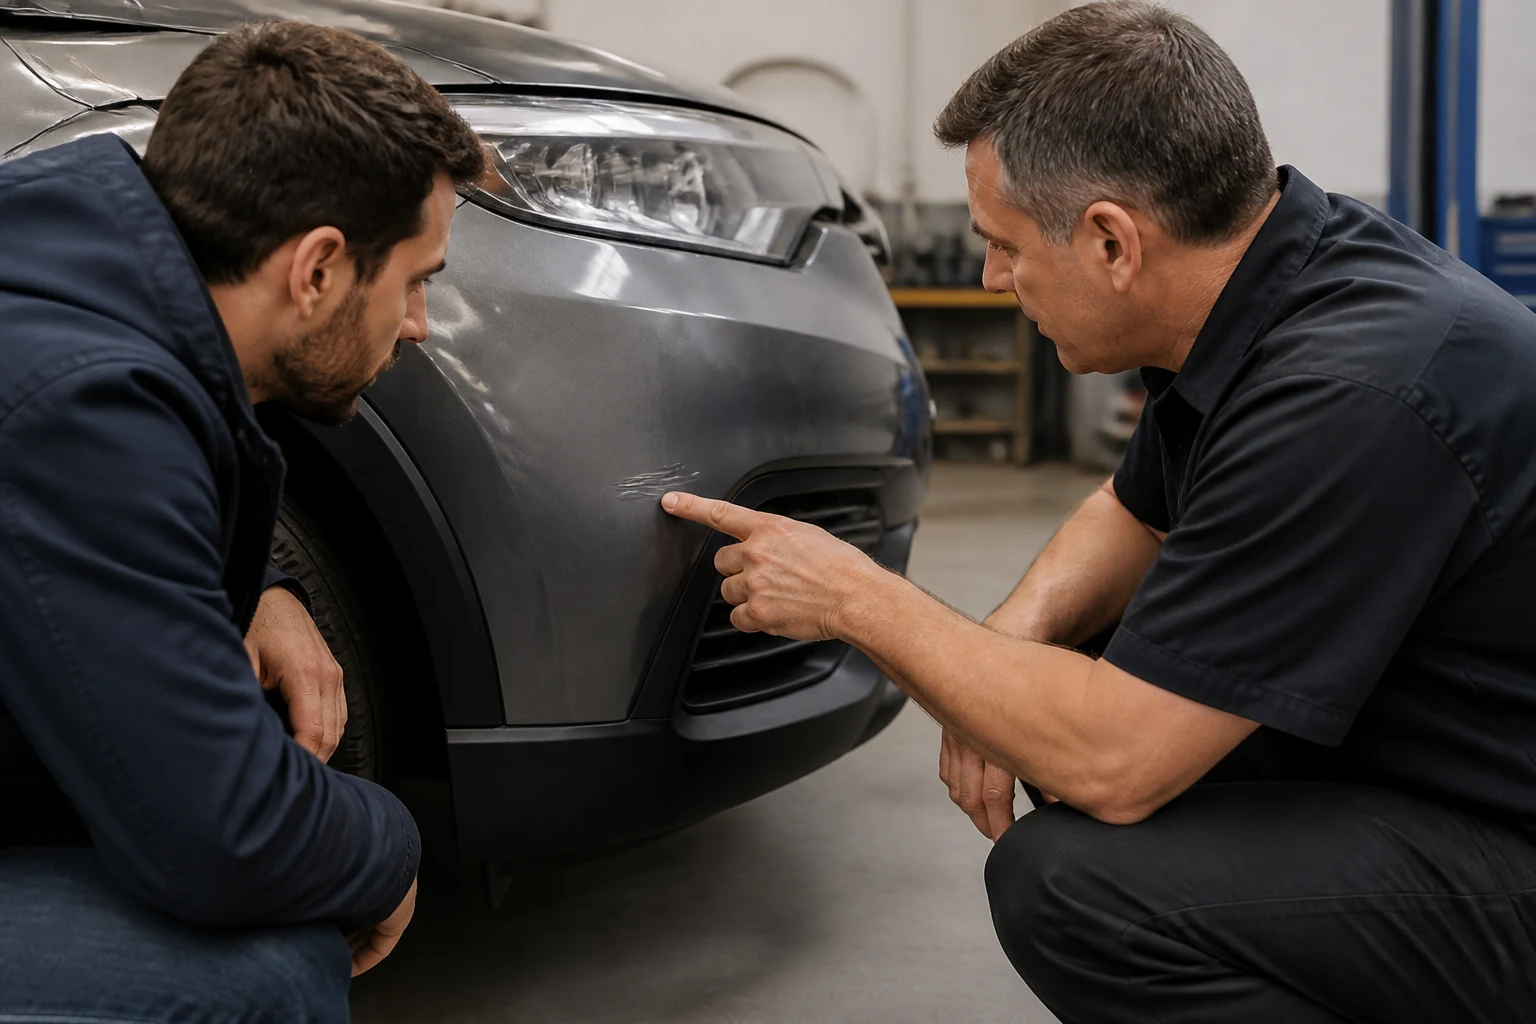
The first step is to understand the main pieces of a car insurance policy. Liability coverage pays for injuries and property damage you cause to others. In many places, it is the minimum legal requirement, but legal minimums are often not enough to protect your finances if a serious crash leads to large claims. Collision coverage helps pay for damage to your own car after a crash with another vehicle or object. Comprehensive coverage applies to non-collision losses such as theft, fire, vandalism, hail, or hitting an animal.
You may also see medical payments coverage or personal injury protection, depending on where you live. These cover certain medical expenses after an accident, sometimes regardless of fault. Uninsured or underinsured motorist coverage can help if the other driver has no insurance or too little. That matters because your own claim may otherwise depend on the other driver’s ability to pay.
A practical way to decide is to separate what the law requires from what your balance sheet requires. If you have substantial savings, you may be able to take on more risk by choosing a higher deductible or dropping collision and comprehensive on an older vehicle. If you do not have much room in your budget, stronger coverage can prevent a single accident from turning into a long-term debt problem. The right answer depends on your car, your commute, your location, and how much disruption you can absorb if something goes wrong.
Match coverage to the value and age of your vehicle
The older and less valuable your car is, the less it may make sense to pay for every available layer of coverage. Collision and comprehensive are most useful when the car has enough remaining value that a repair or replacement payment would matter. If the vehicle is worth only a modest amount, the premium for those coverages can start to look expensive relative to what you could receive after a claim.
That does not mean you should automatically drop these coverages on an older vehicle. Consider whether you could afford to replace the car without disrupting work, caregiving, or daily obligations. If replacement would be a serious problem, keeping broader coverage can still be sensible even when the car is not new. If you can comfortably absorb a loss, you may prefer to self-insure some of the risk by keeping only the coverage you need to satisfy legal and financial requirements.
Your driving pattern matters too. A long commute, heavy city traffic, frequent parking on the street, or travel in areas with severe weather can make comprehensive and collision more valuable. A car that is garaged, driven sparingly, and used mainly for short trips may face less exposure. You are not trying to guess the future; you are trying to compare the likely cost of coverage with the amount of loss you could reasonably handle on your own.
Choose limits and deductibles with your budget in mind
Coverage limits and deductibles are two of the most important levers in a policy. A limit is the maximum the insurer will pay for a covered claim. A deductible is the amount you pay before coverage applies to your own vehicle. Higher deductibles usually lower premiums, but they also increase the amount you must come up with after a loss.
When you set a deductible, be honest about your cash on hand. A deductible that looks manageable on paper may be difficult to pay if you also have towing charges, missed work, or another emergency at the same time. If your emergency fund is thin, a lower deductible may be worth the extra premium. If you have strong savings and want to reduce your monthly cost, a higher deductible may be a reasonable trade-off.
Liability limits deserve just as much attention. The legal minimum may not cover a serious crash, especially if multiple people are injured or several vehicles are damaged. If your policy limit is exhausted, you could be responsible for the rest. The right limit depends on your assets, income, and risk exposure. If you have savings, own property, or have future earnings you want to protect, higher liability limits can be an important part of your personal financial defense.
It helps to think in terms of worst-case affordability, not just monthly premium. Ask yourself whether you could pay the deductible tomorrow, whether you could handle a claim involving another driver, and whether a lawsuit would threaten your savings or wages. Those questions are more useful than comparing quotes alone.
Look closely at exclusions, usage, and how you drive
A policy can look strong until you see the details that narrow coverage. Exclusions are situations the insurer does not cover. Common examples can include intentional damage, racing, using the car for business when the policy is for personal use only, or damage tied to excluded drivers. If you share the vehicle with family members or use it in ways that go beyond ordinary commuting, make sure the policy matches that reality.
Usage matters because insurers price risk based on how the vehicle is used. A car used for short personal trips may be treated differently from one used for daily long-distance commuting or commercial activity. If your situation changes, the policy may need to change as well. For example, moving from occasional driving to regular rideshare work, deliveries, or frequent business travel can create coverage gaps if you do not update your policy.
Your own driving habits also affect what you should prioritize. If you are a cautious driver in a low-traffic area, your claim profile may differ from someone who drives in dense urban traffic or on highways every day. Even so, careful driving does not eliminate the need for liability protection. You are not buying insurance to prove that you are a good driver; you are buying it because even careful drivers can be involved in accidents they did not expect.
Read the policy language on rental reimbursement, towing, glass damage, and roadside help only if those extras fit your needs and budget. These features can be useful, but they should not crowd out more important coverage. The most important question is whether the policy protects the financial risks that would actually hurt you.
Compare policies by the full cost, not just the premium
The monthly premium is only one part of the price. Two policies with similar premiums can behave very differently after a claim because of deductibles, limits, exclusions, and how the insurer handles repairs and payments. The cheapest quote is not always the least expensive choice once you account for what happens if you actually need the coverage.
To compare policies well, line them up by the same basic features. Make sure the liability limits, deductibles, and coverage types are comparable before judging price. Then consider what you are getting for the difference. A slightly higher premium may be worthwhile if it meaningfully improves your protection or reduces your out-of-pocket risk. A lower premium may be fine if it reflects a conscious choice to accept a higher deductible or lower coverage on a vehicle you can replace without strain.
Also think about how a claim would affect your time and cash flow. Repair delays, temporary transportation, and the need to gather documentation can all create indirect costs. Some policy options can help reduce these disruptions, but only if they are relevant to your situation. Do not pay for convenience features you are unlikely to use, but do not ignore them if losing access to your vehicle would create a real hardship.
If you are comparing multiple offers, keep your notes simple and focused on the features that matter most to your finances: liability limits, deductible size, coverage for your own car, uninsured motorist protection, and the extras that fit your driving life. That approach keeps you from being distracted by a quote that looks appealing only because it left out something important.
Use a decision process that fits your financial situation
A sensible policy choice starts with your budget and your reserves. If losing your car would be financially disruptive, you may need broader coverage and a lower deductible. If you have the savings to absorb a loss and your vehicle is modest in value, you might reasonably choose leaner protection and keep more money in your emergency fund. There is no single best answer for every reader.
It can help to ask three questions in order. First, what coverage do you legally need? Second, what coverage do you need to avoid a financial setback you cannot comfortably absorb? Third, what optional coverage improves your daily life enough to justify the cost? This sequence keeps the decision grounded in priorities instead of sales language or habit.
You should also consider how insurance fits into your larger financial plan. If you are paying down debt, building savings, or preparing for a large expense, monthly premium changes matter. A cheaper policy may free up cash, but only if it does not leave you exposed to a loss you cannot cover. Conversely, a fuller policy may be worth the cost if it helps preserve your savings from a major accident.
When your situation changes, revisit the policy. Buying a different car, moving, adding a driver, changing jobs, or moving from city driving to remote work can all affect what you need. Insurance works best when it reflects current reality, not a snapshot from years ago.
The best car insurance is the one that protects you from losses you cannot comfortably handle while avoiding extras that do not fit your needs. If you start with your legal requirements, measure coverage against the value of your vehicle, and set deductibles and limits around your real budget, you can make a decision that is practical rather than generic.